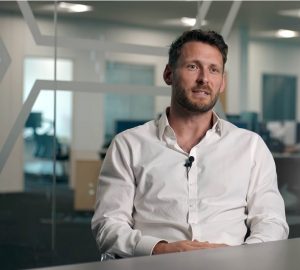
 As the TPI market becomes more competitive and energy procurement increasingly complex, Tritility is expanding its indirect channel proposition. Josh Coleman, Head of Indirect Channel, explains why aggregation should be about more than supplier access – and why operating a direct consultancy need not create conflict with TPI partners.
The job of an independent energy consultant is becoming increasingly complicated. There are more TPIs competing for customers, while gaining and maintaining direct access to a broad range of suppliers is not necessarily getting easier. At the same time, consultants must keep abreast of changing regulation, compliance requirements and an increasingly diverse range of energy products.
For smaller TPIs in particular, doing all of that while maintaining the customer relationships on which their businesses depend can be a significant challenge.
It is against this backdrop that Tritility, which has spent the past eight years developing its own direct energy consultancy business, sees an opportunity to expand its indirect channel.
Josh Coleman, Head of Indirect Channel at Tritility, says the experience of operating as a TPI itself is central to the proposition.
“There’s more competition in the TPI space than ever before,” he says. “At the same time, the job behind the scenes keeps growing. Maintaining strong relationships with 30 or more suppliers, keeping track of how their products and requirements are changing, staying on top of regulation, and then collecting commission from all of them every month, reconciling it against industry data and chasing what’s missing. For a smaller business, that’s a huge amount of work, and it’s all time spent away from customers.”
The opportunity, he argues, is to use the supplier relationships, expertise and infrastructure Tritility has already built to support other consultants.
For Coleman, that also reflects a change in the way TPIs view aggregators.
Historically, aggregation could be seen as something of a necessity – a route to suppliers a consultant could not access directly. Increasingly, he says, TPIs are choosing an aggregator because of the administrative burden it can take off their hands.
Instead of maintaining numerous supplier relationships and portals or individually keeping track of changing requirements, the TPI can lean on the aggregator’s infrastructure.
That frees up time for what Coleman believes many independent consultants do best: looking after their customers.
“TPIs are at their best when they are with their customers,” he says. “They build fantastic relationships with customers and nurture them, and that requires time.”
The channel conflict question
There is, however, an obvious issue for Tritility to address. If the company operates its own direct consultancy, how can an independent TPI be confident that giving Tritility visibility of its business will not ultimately create a competitor for its customer?
Coleman says it is one of the most common questions he receives – and one Tritility has deliberately addressed in the way the operation is structured.
The direct and indirect teams operate separately, using different systems, and the direct sales team has no access to partner customer data. Tritility’s partner agreements also set out that the customer relationship belongs to the TPI, including at renewal.
There is a straightforward commercial rationale too. Tritility has spent years building its direct business and Coleman argues it would make little sense to invest in creating a partner channel only to undermine it by competing for partners’ customers.
Instead, Tritility believes its direct experience is an advantage.
Operating as a TPI has required it to develop supplier relationships, commercial terms, compliance procedures and the processes needed to take contracts successfully from quotation through to go-live. Those capabilities can now be made available to other consultants.
Compliance is becoming particularly important. While TPIs remain responsible for their own activities, Coleman says Tritility can provide guidance around changing requirements and share the practices it has developed within its own business.
More than a route to suppliers
Coleman also believes aggregation needs to move beyond being purely transactional. Feedback he receives from TPIs suggests some aggregator relationships have become dominated by systems, support tickets and contract processing, rather than actively helping consultants develop their businesses.
Technology should make life easier, he argues, but it should not become a barrier between the TPI and the people supporting them. Tritility’s aim is therefore to combine systems and processes with access to people when consultants need assistance.
The complexity behind even a relatively conventional energy contract illustrates the point. Customer information must be checked, contracts validated, compliance requirements satisfied and the process monitored after signature to ensure the supply successfully goes live.
Product selection is becoming more complicated too. The lowest headline price is not necessarily the most suitable contract for a customer. A business planning solar PV, energy-efficiency measures or significant changes to its consumption, for example, may need to consider volume tolerances or take-or-pay provisions alongside the unit rate.
Tritility currently works with more than 30 suppliers, many offering multiple products. Understanding the differences between them and matching those products to an individual customer’s circumstances requires significant resource.
That breadth can also enable smaller TPIs to tackle requirements that might previously have sat outside their comfort zone.
Coleman says Tritility has already supported partners procuring flexible energy contracts for customers – something those consultants may previously have been reluctant to offer because of the complexity involved.
A complementary relationship
Crucially, Tritility is not presenting its proposition as an all-or-nothing alternative to a TPI’s existing relationships.
An established consultant might have excellent direct arrangements with several suppliers but require access elsewhere. Another may want wider support across procurement, compliance and administration.
Coleman describes the proposition almost as a menu: TPIs can use the elements that add value to their existing business rather than dismantling relationships that already work.
That philosophy could become increasingly relevant as the role of the TPI continues to expand.
Procurement remains fundamental, but consultants are increasingly being asked to help customers understand consumption, manage energy costs, navigate regulation and develop carbon and net zero strategies.
Coleman believes greater regulation could actually strengthen that role rather than diminish it, giving knowledgeable TPIs another opportunity to demonstrate their value.
For aggregators, that means the proposition must evolve too.
Supplier access remains important, but the bigger opportunity may be providing the expertise, technology and infrastructure that allows independent consultants to offer more without having to build everything themselves.
For Tritility, the objective is not to replace the relationship between the TPI and its customer. It is to strengthen what sits behind it.